HOME / PERSONAL CREDIT RESTORATION

Compliant, Transparent Personal Credit Restoration.

A structured, educational approach to auditing, challenging, and correcting inaccurate or unverifiable consumer credit data under the Fair Credit Reporting Act (FCRA). We dispute questionable reporting while guiding you toward sustainable credit health.
✓ FCRA & CROA Compliant✓ Real 3-Bureau Audits✓ No Advance Fees Before Work
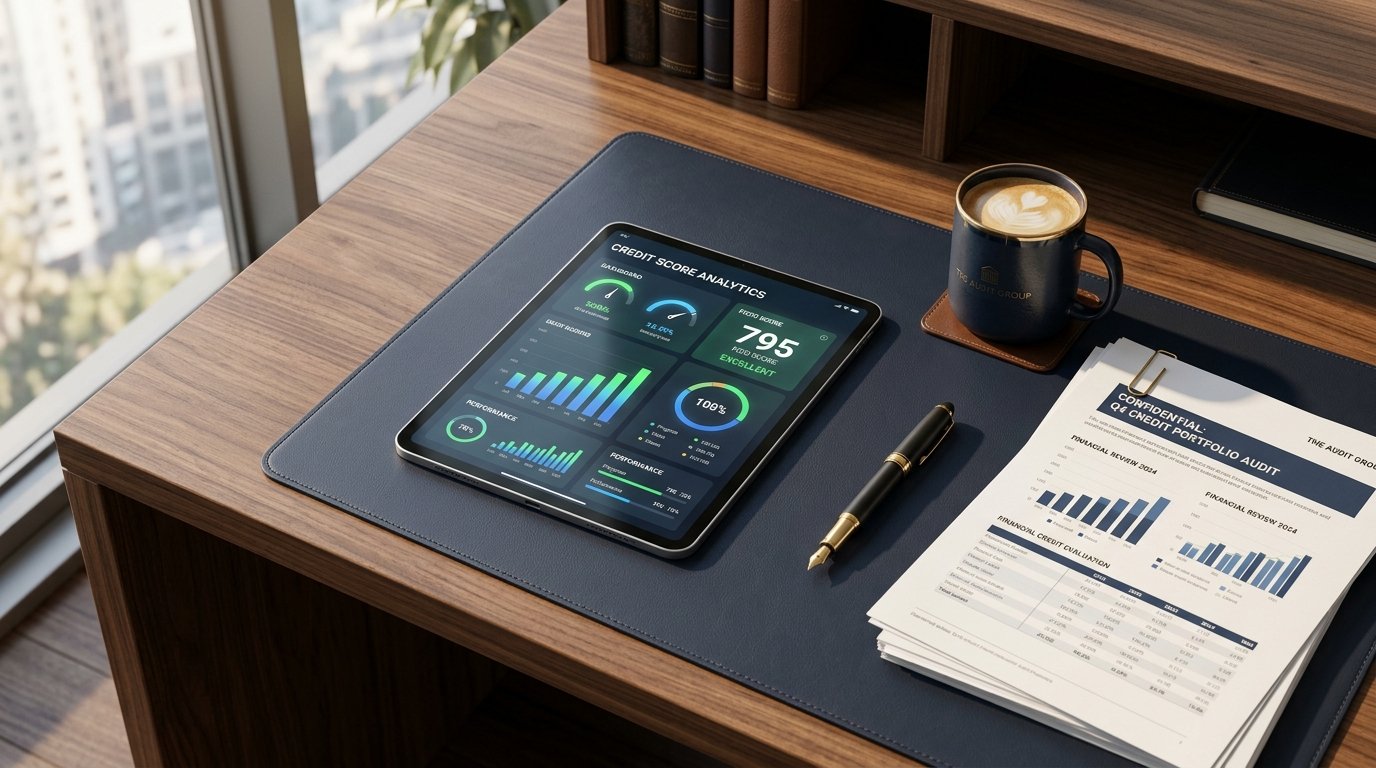
Executive workspace with credit score analytics, 3-bureau audit reports, and tablet
PROGRAM AT A GLANCE

Structured Personal Credit Repair

Program Rate:$199 / cycle (Paid per completed work round)
✓ Experian, Equifax & TransUnion comprehensive audit
✓ Factual dispute drafting for inaccurate items
✓ 24/7 Client Portal with live dispute tracking
✓ Tradeline & utilization optimization coaching
✓ No lock-in contract: cancel anytime with written notice
WHO WE HELP

Designed for Consumers Facing Reporting Inaccuracies

Our personal credit restoration services are built for individuals whose credit scores are burdened by inaccurate, outdated, unverifiable, or misreported credit records across the major bureaus.

Prospective Homebuyers

Preparing for mortgage underwriting by addressing inaccurate derogatory marks, collection records, and balance reporting errors that affect tier eligibility.

Inaccurate Reporting Victims

Individuals dealing with mixed credit files, duplicate creditor accounts, unauthorized inquiries, or miscalculated late payment dates.

Business Owners & Founders

Entrepreneurs strengthening their personal guarantor profile to unlock Tier 2 & Tier 3 commercial credit lines and SBA bank financing.

Post-Hardship Recovery

Rebuilding credit standing after medical emergencies, divorce, or financial disruption through strategic verification and positive tradeline coaching.

METHODOLOGY & STEPS

How Our Restoration Process Works

1

3-Bureau Report Ingestion & Audit

We conduct a comprehensive audit across Experian, Equifax, and TransUnion to isolate inaccurate account statuses, outdated public records, incorrect balances, and unverifiable tradelines.

2

Tailored Factual Dispute Strategy

We draft custom dispute letters citing specific provisions of the FCRA, FCBA, and FDCPA, challenging credit bureaus and data furnishers to verify or remove flawed items.

3

Investigation Tracking & Re-Evaluation

Under federal law, bureaus have 30 days to investigate. We monitor responses, audit updated credit files for deletions or modifications, and prepare subsequent dispute rounds where needed.

4

Positive Tradeline & Score Optimization

Removing inaccuracies is only half the equation. We guide you on credit utilization ratios, positive primary tradelines, and payment sequencing to build resilient credit profiles.
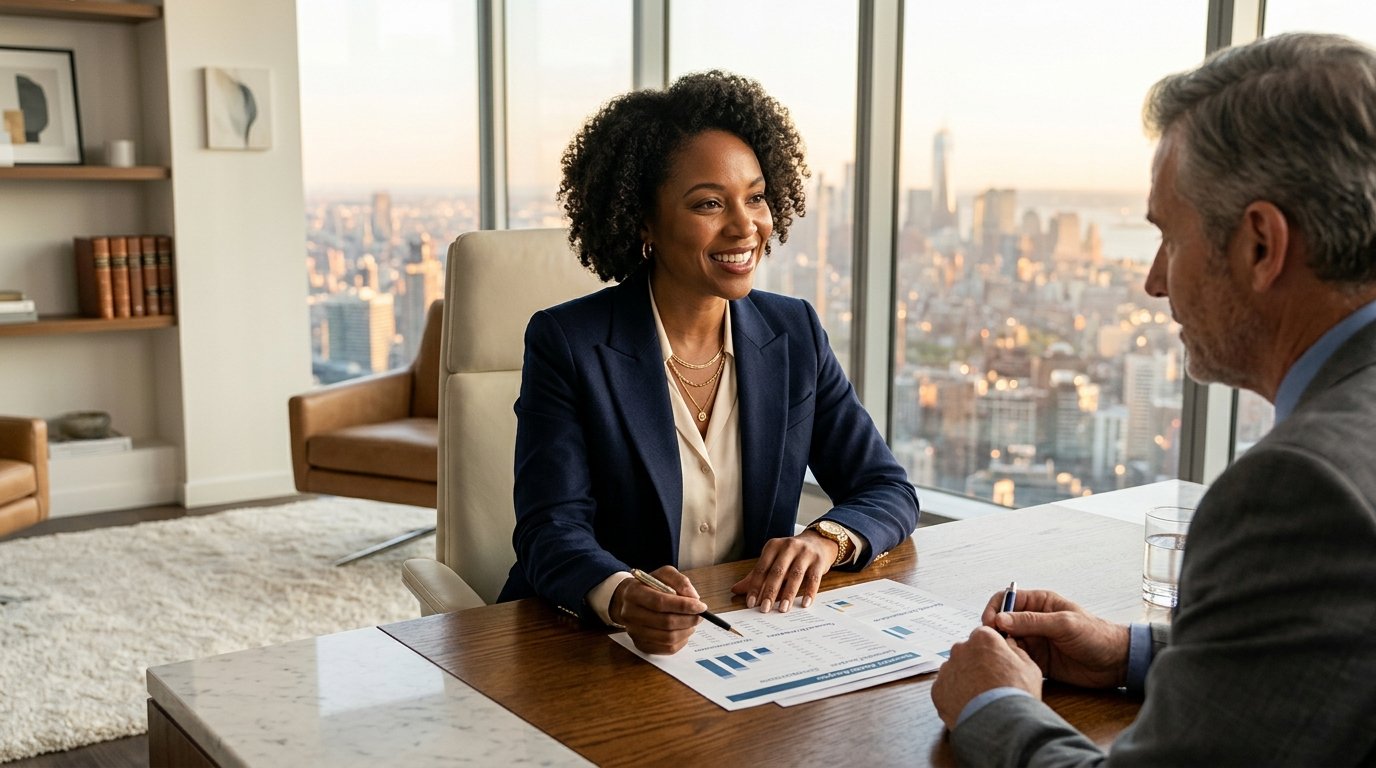
Professional credit advisor reviewing financial records and credit reports with client
CLIENT DELIVERABLES

What You Receive in Every Cycle

  • ✓ Line-by-Line 3-Bureau Audit: Detailed breakdown of negative reporting factors.
  • ✓ Custom Legal Dispute Drafting: Tailored challenges sent directly to repositories.
  • ✓ Direct Creditor / Furnisher Challenges: Interventions where furnishers misreport balances.
  • ✓ Secure 24/7 Portal Access: Real-time progress updates and document vault.
  • ✓ Monthly Progress Reviews: Review of bureau replies and next-round planning.
  • ✓ Credit Building Advisory: Concrete steps to build positive tradeline depth.
TRANSPARENT PRICING

Fair, Transparent Investment with Zero Advance Fees

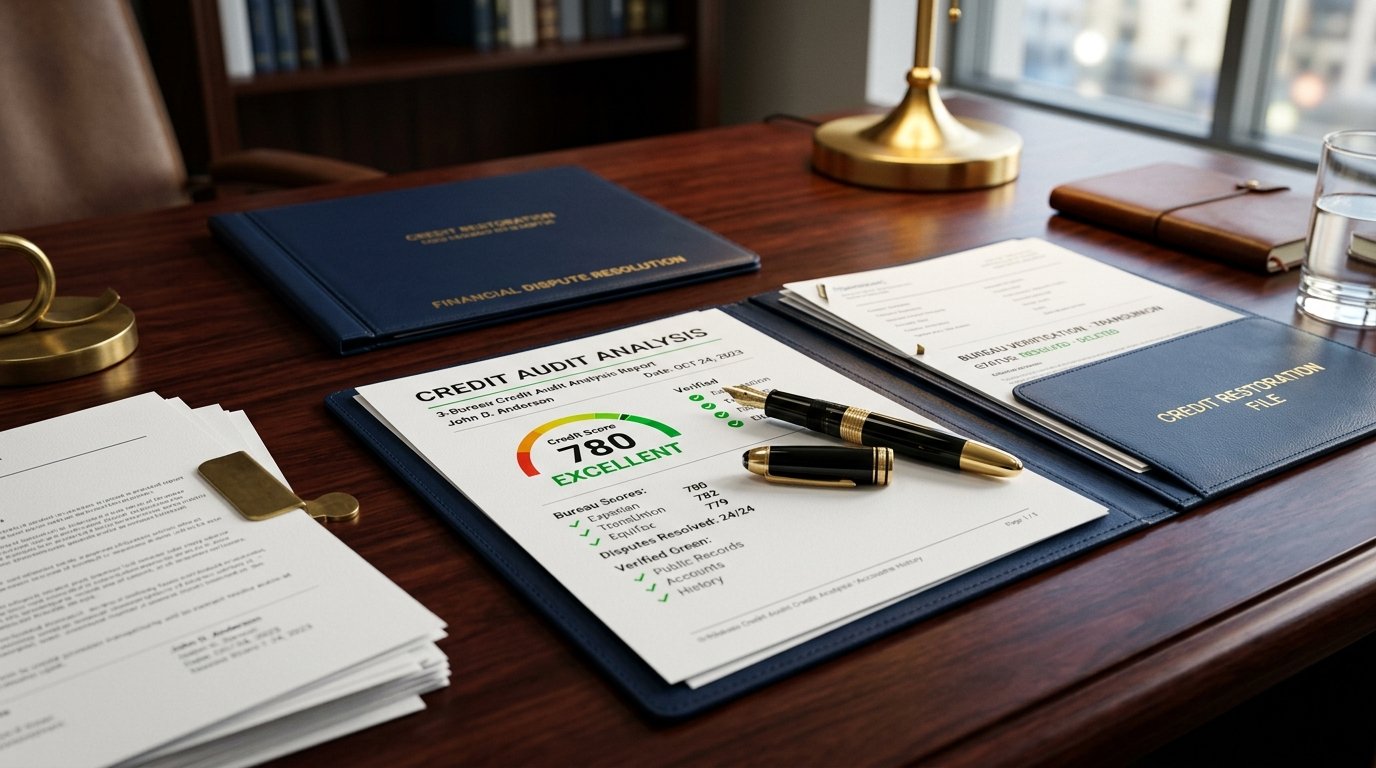
Credit audit review with positive score trajectory, reports, and dispute documentation
Active Service Program

Personal Credit Restoration Program

Includes continuous 3-bureau file auditing, customized dispute round preparation, bureau response evaluation, client portal management, and tradeline coaching.

Notice: Fully compliant with CROA advance fee restrictions. Fees are billed strictly after initial dispute preparation work is executed. No long-term lock-in contract.
$199
Per Service Cycle
Start Assessment →
CLIENT READINESS

What You Need to Prepare Before Getting Started

To ensure a seamless, legally compliant audit and avoid delays with the credit repositories, please have the following items ready for your onboarding specialist.

1

3-Bureau Credit Monitoring

Active account with an approved monitoring service (e.g., SmartCredit or IdentityIQ). This enables importing your 3-bureau report without triggering hard inquiries or score deductions.

2

Government-Issued Photo ID

A clear, unexpired color copy of your Driver’s License, State ID, or Passport. Credit bureaus legally mandate consumer photo verification before investigating dispute submissions.

3

Proof of Physical Address

A utility bill (electric, water, or gas), cable bill, or bank statement dated within the last 60 days matching the physical address on your current photo ID.

SERVICE FAQ

Frequently Asked Questions About Personal Credit

Understand your legal rights, timelines, and how the consumer credit restoration process works under federal compliance standards.
Client care credit advisor with headset ready to assist clients with personal credit questions
Personal credit repair operates on statutory 30-day investigation cycles set by federal law. Most files show progress within 3 to 6 dispute cycles depending on the volume of inaccurate records, creditor cooperation, and bureau responsiveness. Credit restoration is an iterative legal process that requires patience and methodical execution.
No. Under the Fair Credit Reporting Act (FCRA) and the Credit Repair Organizations Act (CROA), no company or individual can legally delete accurate, verifiable, and timely credit information. Our service focuses exclusively on auditing, challenging, and correcting unverifiable, incomplete, inaccurate, duplicate, or outdated reporting notations.
No. Federal law strictly prohibits credit repair organizations from making false promises or guaranteeing specific score increases. Credit scores are determined by proprietary algorithms (FICO and VantageScore) based on ongoing payment timeliness, credit utilization, length of history, account mix, and inquiries. We guarantee our work, process integrity, and diligent legal challenges, not algorithmic outcomes.
No. When you provide access to your credit monitoring account (such as SmartCredit or IdentityIQ), it constitutes an educational soft credit inquiry (consumer disclosure pull). Soft inquiries have zero impact on your credit scores and do not appear to lenders who review your profile in the future.
Yes. Under federal CROA provisions, you have the right to cancel your contract at any time with 3 business days’ written notice without any penalty or obligation. You are only billed for services already performed in completed dispute rounds.
STATUTORY CONSUMER NOTICE

Consumer Credit File Rights Under Federal Law

Consumer Rights Disclosure: You have the legal right under federal law (Fair Credit Reporting Act, 15 U.S.C. § 1681) to dispute inaccurate information in your credit report by contacting the credit bureaus directly at no charge. You are also entitled to receive a free copy of your credit report from AnnualCreditReport.com once every 12 months from each national bureau (Experian, Equifax, TransUnion), or if you have been denied credit within the past 60 days.

Credit Repair Organizations Act (CROA, 15 U.S.C. § 1679): Credit repair organizations are prohibited by federal law from demanding or receiving payment for services before those services are fully performed. Our fees are billed solely for work executed during completed dispute cycles. No credit repair service has the legal authority to remove accurate, verifiable, and timely negative information from your credit file.

Non-Lender Status: Credit restoration services are consulting and educational services. We are not a direct lender, bank, or loan broker. We do not extend credit, originate loans, or make underwriting determinations. For comprehensive statutory details, view our Required Credit Disclosures.

Take the First Step Toward Credit Confidence

Request your personalized credit and funding assessment today. Our specialists will audit your file, clarify realistic timelines, and outline your dispute roadmap.